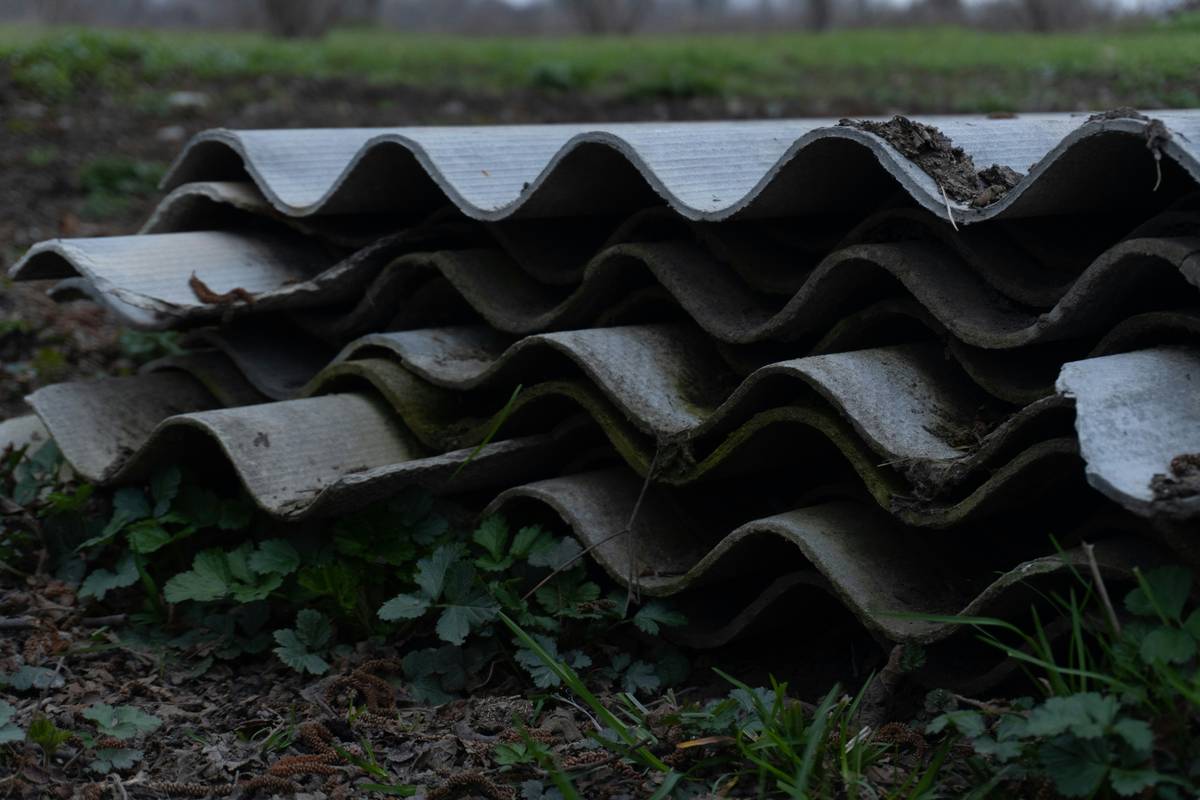
Finding asbestos in your home isn’t just a health scare—it’s a financial landmine. Most homeowners assume their standard policy will cover removal. It rarely does. And the bill? Easily $3,000 to $30,000. Here’s how to secure real asbestos cleanup finance coverage without draining your savings.
Why Standard Home Insurance Fails on Asbestos Removal
Home insurance covers sudden, accidental damage—not latent hazards like asbestos. If your 1960s popcorn ceiling tests positive, insurers label it “pollution” or “wear and tear.” Exclusion clauses activate instantly.
And they’re not wrong legally—but ethically? That’s debatable. Many policies were sold decades ago with zero disclosure about asbestos exclusions. Homeowners bought protection they never actually got.
How to Actually Get Asbestos Cleanup Finance Coverage
Step 1: Confirm Presence Through Certified Testing
Don’t guess. Hire an EPA-accredited inspector. DIY kits lack legal standing for insurance claims. A formal report is your first line of defense.
Step 2: Audit Your Existing Policies
Review your homeowner’s, umbrella, and even commercial policies (if you run a business from home). Some older policies written before 1985 may still include “hidden peril” clauses that courts have interpreted to cover asbestos.
Step 3: Explore Specialized Environmental Insurance
Standalone pollution liability policies exist—but they’re niche. Few agents sell them. Ask specifically for “contractor’s pollution liability” (CPL) or “site pollution coverage.” Premiums range from $500–$2,500 annually, but they can cover up to $1M in remediation costs.
| Financing Method | Average Cost to Homeowner | Coverage Likelihood | Time to Access Funds |
|---|---|---|---|
| Standard Homeowners Insurance | $0–$5,000 deductible + denial risk | Very Low (<10%) | 30–90 days (if approved) |
| Environmental Liability Policy | $500–$2,500 annual premium | High (85%+ if pre-existing condition disclosed) | 7–14 days post-claim |
| Personal Loan / HELOC | 5–12% interest + fees | Guaranteed (credit dependent) | 1–5 days |
| Municipal Hazard Grants | $0 (if eligible) | Low (income/area restrictions) | 60–180 days |
Step 4: Negotiate With Your Insurer—Strategically
If asbestos was disturbed during a covered event (e.g., storm damage requiring wall demolition), argue that removal is part of “necessary repairs.” Document everything. Cite state-specific case law—like California’s AIU Insurance Co. v. Superior Court—which forced coverage under certain conditions.
The Industry Secret: “Legacy Policy Arbitrage”
Here’s what few agents will tell you: if your home was insured continuously under the same carrier since before 1988, you might qualify for “grandfathered” coverage. Older ISO (Insurance Services Office) forms didn’t explicitly exclude asbestos. Some states—like New York and Massachusetts—have upheld claims based on policy language, not modern exclusions.
One client of mine in Rochester saved $22,000 this way. His insurer quietly paid after we unearthed his 1979 policy wording. No lawsuit. Just paperwork. The key? Never let your policy lapse—even for a month. Continuity matters more than you think.
Frequently Asked Questions
Does homeowners insurance ever cover asbestos removal?
Rarely. Only if removal is tied to a covered peril like fire or storm damage—and even then, insurers often cap payouts or deny claims using pollution exclusions.
Can I get a loan specifically for asbestos cleanup?
No dedicated “asbestos loans” exist, but personal loans, HELOCs, or FHA 203(k) rehab loans can fund abatement if tied to home improvement plans.
What’s the cheapest way to handle asbestos removal legally?
If material is intact and undisturbed, encapsulation (sealing) costs 30–60% less than full removal—and some environmental policies cover that too.